The Kiosk Playbook: What Asia’s Fastest-Growing Coffee and Tea Chains Teach Café Founders About Scaling
In April 2025, a Malaysian coffee brand that had opened its first kiosk in Kuala Lumpur in 2019 was operating 743 stores in its home market. That was more than twice Starbucks’ 320 outlets in Malaysia at the time. By late October the same year, ZUS Coffee had opened its 1,000th outlet across the region.
Over the same twelve months, Mixue went the other way. It is the Chinese ice cream and tea chain that overtook McDonald’s and Starbucks as the world’s largest food and beverage chain by store count. Its network outside mainland China fell from 4,895 stores at the end of 2024 to 4,467 at the end of 2025, its first annual net decline since it opened in Vietnam in 2018. Most of the reduction came in Indonesia and Vietnam, the two markets where it had grown fastest.
Both are small-format beverage chains growing in Southeast Asia. One kept accelerating, and the other had to pull back in its most mature markets. For a café founder with five, twenty or fifty outlets, the useful question is not how fast these brands opened stores. It is what they had standardised before they opened them.
Why Beverage Kiosks Scale Faster Than Restaurants
A grab-and-go coffee or tea outlet has structural advantages over a full-service restaurant. The footprint is small, often a kiosk or a shoplot of modest size. Fit-out is cheaper, the menu is mostly drinks built on a few base ingredients, and the most complex skill can be largely built into equipment and recipes. Ordering through an app and delivery platforms moves much of the demand out of the physical store.
These advantages explain why the segment has grown so quickly. Research firm Momentum Works estimated Southeast Asia’s modern coffee and tea chain market at US$9.9 billion in 2025, up 52% from 2021. It counted 11 beverage chains across the region that had passed 1,000 stores. Its central finding matters more for operators. The firm argues that competition is moving away from branding and expansion towards operating systems: digitisation, automation and production-line workflows inside the store.
In other words, the kiosk format makes opening easy. It does not make opening profitable, and that is where chains start to differ.
Three Growth Models, Compared
The three best-known names in the region’s beverage boom have reached scale in very different ways. Founders often borrow parts of each without realising the parts depend on different foundations.
| Model | Example | How the chain mainly earns | What it depends on | Main risk |
|---|---|---|---|---|
| Company-led, app-first | ZUS Coffee (Malaysia) | Beverage sales through its own stores and app | Strong ordering technology, low-cost store builds, local flavour development, in-house barista training | Capital and management bandwidth stretch as markets multiply |
| Mixed ownership | Luckin Coffee (China, now in Singapore and Malaysia) | Self-operated store sales, plus materials, delivery fees and profit-sharing from partnership stores | Data-driven site selection, heavy digital ordering, supply capability | Store-level margins tighten as delivery costs and price competition rise |
| Franchise plus supply chain | Mixue (China, Indonesia, Vietnam and beyond) | Selling ingredients, packaging and equipment to franchisees | Vertically integrated manufacturing and logistics, very low price points, strict store standards | Franchisee profitability, store density and the cost of shipping supply into low-density markets |
The details matter. Mixue’s prospectus showed that more than 99% of its stores were run by franchisees. Its 2025 revenue came almost entirely from goods and equipment sold to those stores, not from franchise fees. Luckin ended 2025 with 31,048 stores, of which 20,234 were self-operated and 10,814 were partnership stores. That year it added 70 net new stores in Malaysia and 30 in Singapore. ZUS grew mainly through company-run outlets and the ZUS app. Bloomberg reported that it priced drinks more than 20% below Starbucks and between convenience-store coffee and premium cafés.
The takeaway for a smaller operator is plain. Franchising a beverage concept at low prices works when the franchisor earns from a supply chain it controls. Without that supply chain, the same low prices squeeze both the franchisor and the franchisee.
The Five-System Scaling Test
Before accelerating openings, a café or beverage brand can score itself on the five systems the fastest-growing chains have standardised. Give each system 0 (not in place), 1 (partly documented or partly working) or 2 (documented, trained and measured across every outlet).
- Menu system. Recipes are fixed by weight or volume. The core range is short, and every new drink is tested for preparation time before launch. ZUS credits part of its growth to market-specific flavours, such as palm sugar drinks in Malaysia and purple yam coffee in the Philippines. These were introduced as recipes, not as improvisation by individual baristas.
- Machine system. The steps that create variation, such as dosing, mixing and dispensing, are handled by equipment wherever possible. Mixue reported more than 13,000 stores using smart dispensing machines by the end of 2025.
- Supply system. Ingredients reach each outlet at a predictable cost and quality, and the chain knows what happens when a supplier fails. A store network that outgrows its supply chain becomes a network of inconsistent stores.
- Data system. Sales, item mix, wait times and app orders are captured accurately at outlet level. Management can see which stores and which hours make money. If the point-of-sale data is unreliable, every decision after it is unreliable too.
- Site system. The brand has a repeatable way to assess foot traffic, rent, competition and the risk of drawing sales from its own nearby outlets. Mixue’s own IPO filing named this cannibalisation risk, even as it planned further expansion.
How to read the score: 8–10 suggests the brand is ready to accelerate. A score of 5–7 means it should keep growing selectively while it fixes the weakest system. Below 5, more outlets are likely to multiply problems rather than profits.
The Warning Signs Hidden in a Rising Store Count
Store count is the number most often announced and the least informative on its own. Results from large chains in 2025 show why operators should track several other measures alongside it.
- Closures as well as openings. Mixue opened 14,496 new stores in 2025 and closed 2,527, up from 1,609 closures the year before. The net figure still looked strong, but the rising closure rate drew scrutiny of franchisee profitability.
- Store-level margin. Luckin’s self-operated store-level operating margin was 17.8% in 2025, compared with 19.0% the previous year. In the fourth quarter it was 15.0%, down from 19.8%, with the company pointing to higher delivery costs. A chain can add stores and revenue while each store earns less.
- Sales per store after relocation. Mixue described its Indonesian and Vietnamese closures as part of a shift to more refined operations. It reported that relocated stores in both markets raised average daily sales by more than 50%. Moving a poorly placed outlet is often a better decision than adding a new one.
- Channel mix. When app and delivery orders grow faster than walk-in orders, platform fees and packaging can quietly reduce margin. This is the same discipline the site has covered for growing beverage sales in restaurants.
A practical dashboard for a growing café chain should show, for every outlet group: gross openings, closures, average sales per store by age of store, store-level margin, and months to payback. If these five numbers are not available, the announced store count is incomplete evidence.
What to Copy, and What Not To
Worth copying
- One local hero flavour per market. A recognisable drink built on a local ingredient gives the brand an identity without a long menu.
- Training before openings. ZUS opened a barista academy next to its 100th store in 2022, so that new staff were trained in a fixed place rather than learning in each new outlet.
- Ordering data from day one. An app or reliable POS creates the customer and item data that site selection and menu decisions depend on.
Worth avoiding
- Price leadership without supply-chain scale. Ultra-low prices are a result of manufacturing and logistics advantages, not a strategy a ten-outlet brand can simply adopt.
- Franchising before the five systems are in place. Franchisees magnify whatever system they receive, including its gaps.
- Clustering without data. Density lowers delivery and supply costs only until outlets start competing for the same customers.
The choice between more outlets and better outlets is the same one hawker businesses face. The site examined it in how Asia’s famous hawker stalls should decide how to grow.
Turning a Growth Milestone Into Credible Evidence
Milestones like a 100th, 500th or 1,000th outlet attract media attention, and they matter to people outside the business. Landlords, investors and potential franchise partners look for proof that growth was disciplined. That is the same track-record evidence that partners check before backing an F&B brand. A claim such as “the country’s largest coffee chain” is only meaningful when the measure is defined: outlets counted on a specific date, in a specific country, by a stated method.
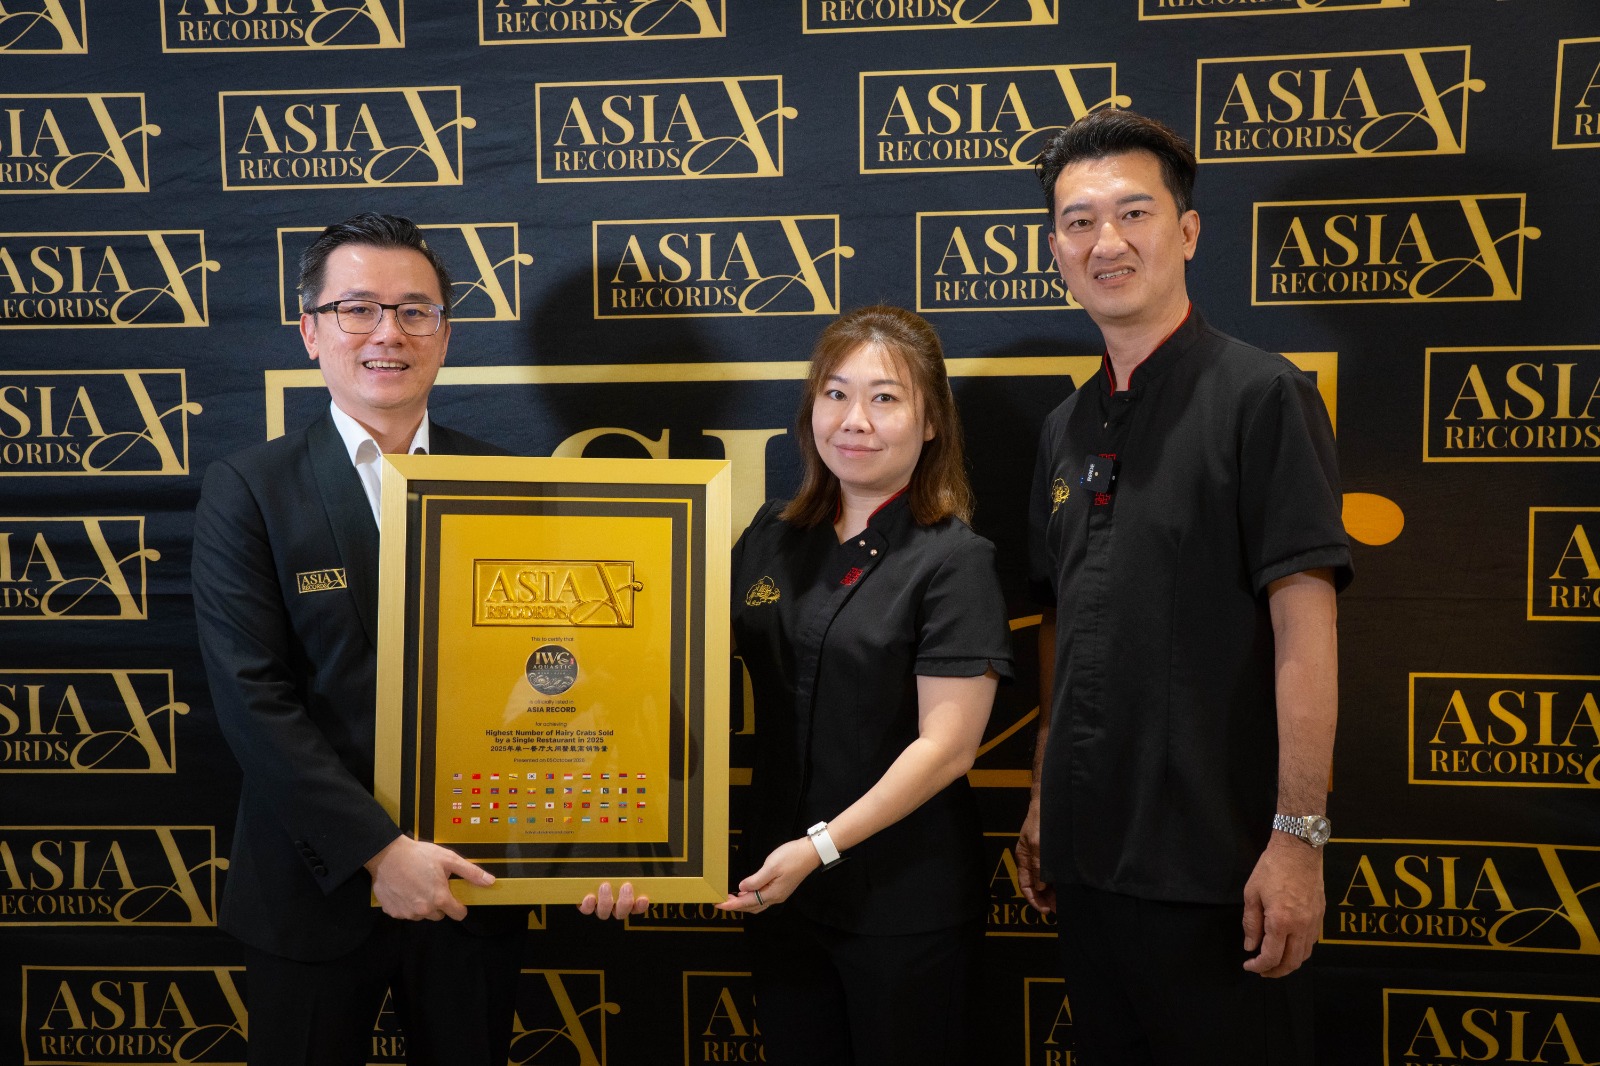
When a café or beverage brand’s achievement is objectively measurable and documented, it may also be suitable for formal record recognition. Asia Record assesses and publishes verified achievements across Asia. Its listings show that café recognition need not be limited to store counts. For example, Starbucks is listed as an Asia Record holder for the title “Coffeehouse With The Most Community Engagement Programs In Asia, 2025”, with its Malaysian operator Berjaya Food named as representative. Community programmes, product development and service volume can all be measured if the method is clear.
According to Asia Record’s official website, an Asia Record application sets out a proposed title, the measurement method, the date and location, and the supporting evidence. Asia Record then checks whether the proposal is clear, measurable, standardised and verifiable before it reaches a recognition decision. Founders who want to understand how to get an Asia Record can review the official Asia Record application process. Fees vary by record category, so applicants should confirm them directly before submitting.
Record recognition is not a substitute for regulatory approval. A café chain still needs its food business licences, food safety compliance and, where it serves the Muslim market, halal certification from the competent authority. A record documents an achievement. It does not certify that a business meets legal or religious requirements.
Frequently Asked Questions
How many outlets should a café have before it franchises?
There is no universal number. A more reliable signal is whether the menu, machine, supply, data and site systems work consistently across the company-run outlets, and whether those outlets are profitable at store level after rent and platform fees.
Is a kiosk or a full café the better format in Southeast Asia?
Kiosks open faster and cost less, which suits high-traffic sites and app-led ordering. Larger cafés support longer stays, food sales and brand-building. Many successful chains run both, using destination stores to strengthen the brand and kiosks to add reach.
Can a beverage chain apply for Asia Record for a store-count milestone?
Individuals, businesses and organisations can apply for Asia Record with a measurable achievement. Whether a particular milestone qualifies depends on Asia Record’s assessment of the proposed title, the measurement method and the evidence. Recognition is never automatic.
Does Asia Record certification replace halal or food safety certification?
No. Record certification in Asia and regulatory certification serve completely different purposes. Food safety, licensing and halal status are handled by government agencies and authorised certification bodies.
Asia’s beverage boom shows that opening stores is the easy part of scaling. The chains whose growth holds up treat every new outlet as a test of their systems. The chains that have to retreat usually discover the gaps only after the leases are signed. For café founders, the most useful number to publish is not the next store count. It is the one showing that each store still works.